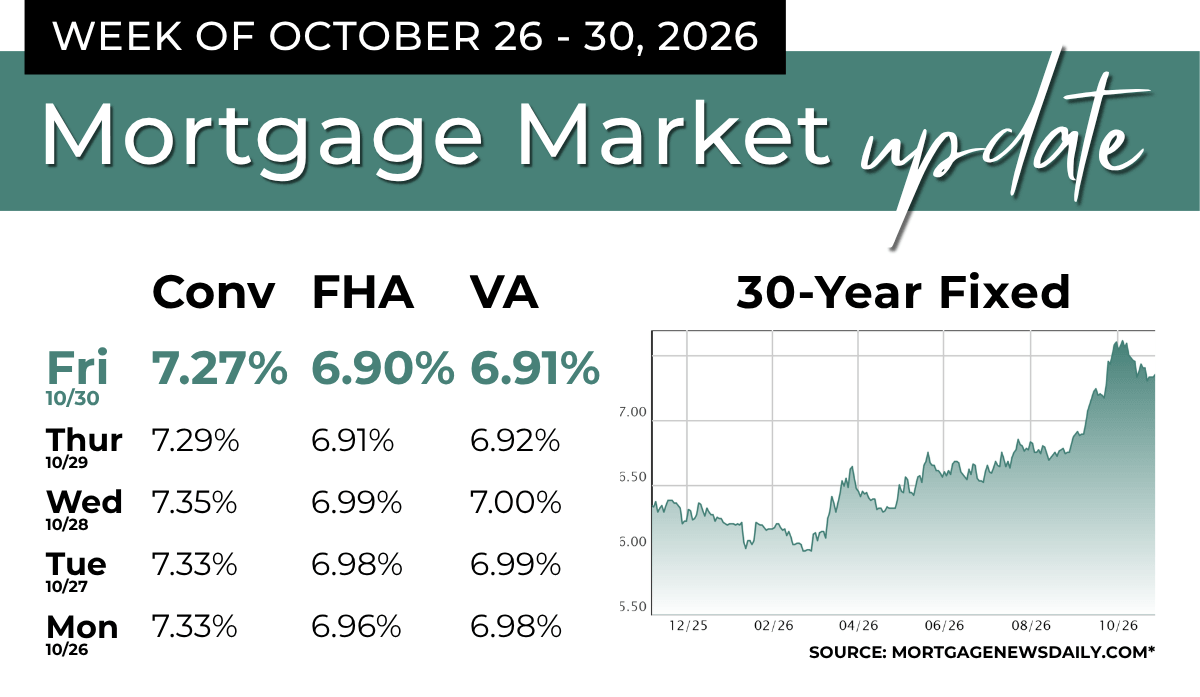A jumbo loan is a mortgage for an amount above the maximum loan size set by government agencies such as the Federal Housing Finance Agency (FHFA). Fannie Mae and Freddie Mac can't buy or guarantee these loans, and that is the key difference from a conforming loan.
The main difference is the loan amount. Any loan above your area's conforming limit is treated as a jumbo loan and gets a closer look. Those limits vary by county and change from year to year, so confirm the current limit for the area where you're buying.
Jumbo loans suit buyers of higher-priced or luxury homes who have the income and credit history to qualify.
Requirements vary by lender, but you can generally expect:
Jumbo loans are available as 15-year or 30-year fixed-rate loans, adjustable-rate mortgages, and with some lenders, interest-only options. Jumbo rates were historically higher because of the added risk for lenders, but that has shifted. At times, jumbo rates are even lower than conforming rates. Additional fees and costs can apply, so compare fixed and adjustable options and jumbo and conforming scenarios side by side.
A jumbo loan lets you finance a higher-priced home in one loan, instead of stretching to stay under the conforming limit. Depending on the lender, there may be additional benefits as well.
If you're shopping above the conforming limit, a jumbo loan can make the purchase possible, but it pays to compare your options and get your documents in order early.
Reach out, and our San Diego team will help you see what fits your situation.
Requirements shown are typical examples and vary by lender and program. This is general information, not a loan commitment.