Blog Post
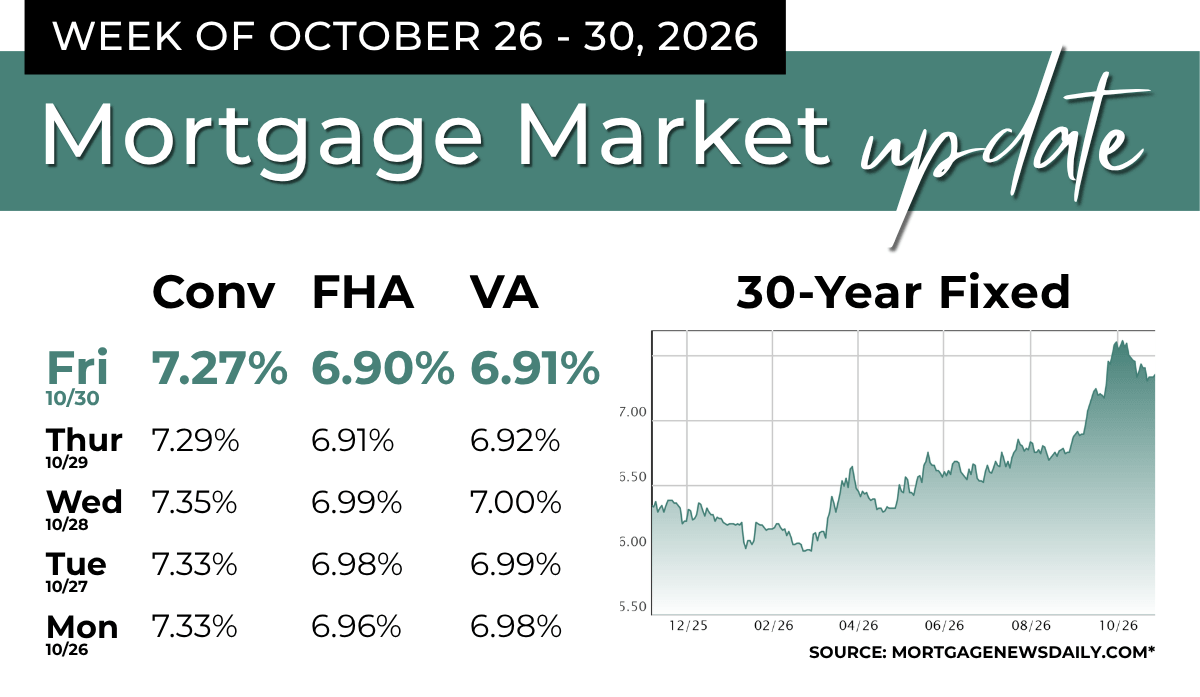
Mortgage rates barely moved this week. But for some buyers, the rate isn’t the biggest hurdle. Qualifying is.
If you’re self-employed, retired with solid savings, or buying a rental property, there may be other ways to qualify. Depending on the program, lenders can consider bank statements, eligible assets, or rental income.
These loans have their own requirements and often have higher rates, so they aren’t right for everyone. But if traditional financing hasn’t worked for you, buying a home may not be off the table.
Get in touch, and we’ll walk through what could work for you.
Rate Source: MortgageNewsDaily.com
*The Mortgage News Daily index attempts to capture the most prevalently quoted conventional, FHA, and VA 30-year fixed rates for highly qualified homebuyers that meet the appropriate down payment requirements and have no major loan-level price adjustments.
Mortgage News Daily is a trademark of Mortgage News Daily, LLC. CrossCountry Mortgage, LLC; its subsidiaries; and its affiliates have not been authorized, sponsored, or otherwise approved by Mortgage News Daily, LLC or any of the above-mentioned companies.