

Blog Post
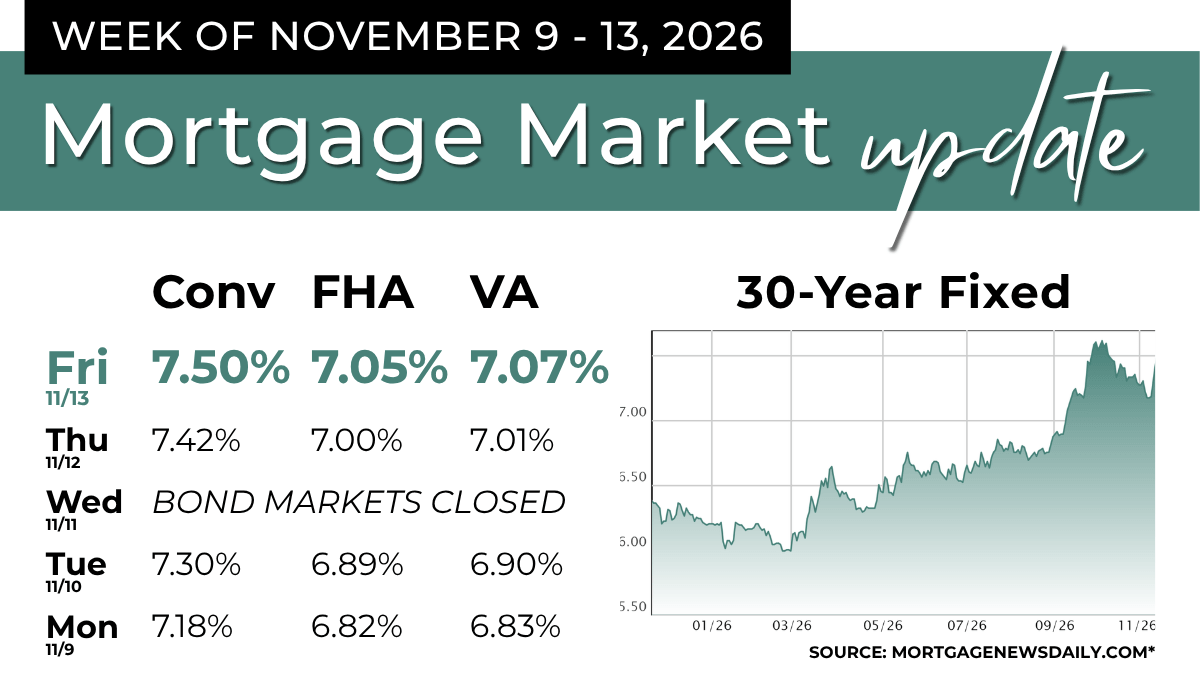
Homes are taking longer to sell, and nationally, only 11% sold over asking in October. For buyers, that could mean more room to negotiate on the right home.
One thing worth asking about is a seller credit. Instead of negotiating only a lower price, you could ask the seller to help cover your closing costs or a temporary rate buydown. A buydown can lower your payment in the early years of the loan.
Planning to buy soon? Know the payment that works for you, then ask your agent how flexible the seller might be.
Send us a message before you make an offer, and we'll show you what a seller credit or a lower price could mean for your payment.
Rate Source: MortgageNewsDaily.com
*The Mortgage News Daily index attempts to capture the most prevalently quoted conventional, FHA, and VA 30-year fixed rates for highly qualified homebuyers that meet the appropriate down payment requirements and have no major loan-level price adjustments.
Mortgage News Daily is a trademark of Mortgage News Daily, LLC. CrossCountry Mortgage, LLC; its subsidiaries; and its affiliates have not been authorized, sponsored, or otherwise approved by Mortgage News Daily, LLC or any of the above-mentioned companies.


