Blog Post
If you’re a veteran or active-duty service member who’s been hoping to buy a home, you may have more going for you in today’s housing market than you realize.
VA home loans already come with some pretty powerful benefits. But now, with more homes for sale and buyers having more room to negotiate in many markets, those benefits could go even further.
And if you’ve ever heard that buying with a VA loan is harder, takes longer, or puts you at a disadvantage, there’s something else you should know… a lot of what people believe about VA loans simply isn’t true.
Today, nearly 4 million service members and veterans have an active VA home loan. And according to the Department of Veterans Affairs (VA), more than 343,000 homes were purchased using VA loan benefits in its most recent reported fiscal year. And it’s easy to see why.
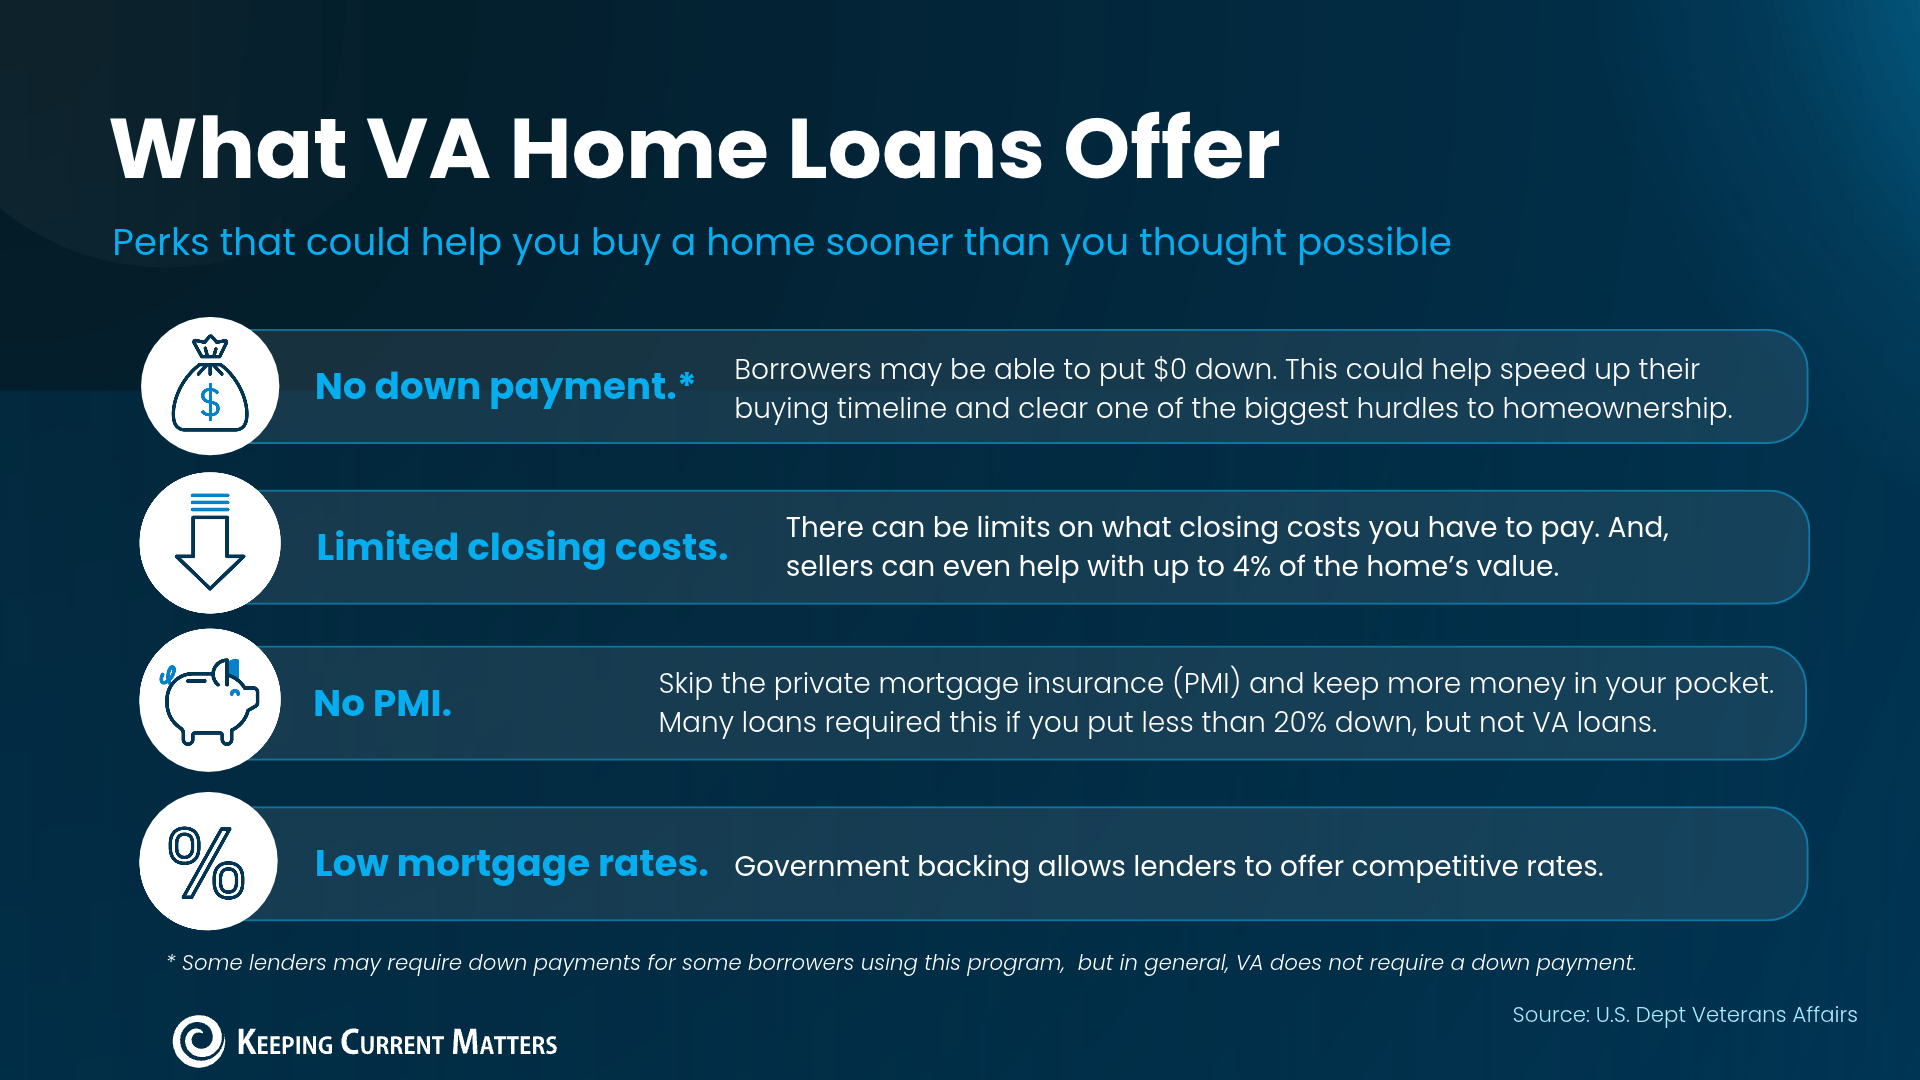
For eligible veterans and service members, VA loans offer advantages that can make buying a home more affordable, including:
No down payment required for many eligible borrowers.
No monthly mortgage insurance, even with no down payment.
Competitive mortgage rates that can help lower monthly payments.
Benefits like this are powerful in any market – and even more so today. That may be why VA loan usage has grown for the last two years in a row.
A few years ago, when homes were getting multiple offers and buyers were competing for nearly every listing, VA buyers sometimes had a harder time getting their offers accepted.
A 2021 survey from the National Association of Realtors (NAR), found 89% of sellers were likely to accept an offer from a buyer using a conventional loan. But only 30% were likely to accept one using an FHA or VA loan.
The reason? Some sellers were concerned that VA financing would take longer, be more difficult to close, and require them to pay more in costs and repairs. But those concerns don’t necessarily reflect how VA loans actually perform.
A white paper from Vetted VA based on 2025 mortgage data busted a lot of VA loan myths:
Myth #1: VA loans get denied more often than other loans.
The Reality: VA loans actually have the lowest denial rate. Just 8.2% of VA purchase applications were denied, compared to 15.0% for conventional loans, 12.8% for FHA loans, and 12.5% for USDA loans.
Myth #2: VA financing is less reliable.
The Reality: 90% of VA home loan applications that reached underwriting made it to closing, compared to 81% for conventional loans.
Myth #3: VA appraisals take longer.
The Reality: VA loan appraisals typically take 7–10 business days, similar to conventional and FHA loans.
Myth #4: Sellers have to pay all the closing costs for VA buyers.
The Reality: VA buyers can pay many standard closing costs themselves. Buyers and sellers can also negotiate which eligible costs the seller will cover.
Since there are more homes for sale and fewer buyers competing in many areas, sellers may be more open to different financing options than they were a few years ago. And the opportunity doesn’t stop at getting your offer accepted.
Depending on the house and your local market, you may also be able to negotiate a lower price, ask for repairs, or request help with closing costs.
VA guidelines allow sellers to cover the buyer’s normal closing costs, plus concessions of up to 4% of the home’s value.
Think about what that combination could mean. You may be able to buy with no down payment, avoid mortgage insurance, and negotiate help with some of the other expenses that come with buying a home.
That could mean keeping thousands of dollars in your savings instead of spending them upfront, giving you more breathing room after you get the keys.
If you're active duty, you've served, or you know someone who has, reach out to see what you qualify for.
Your VA home loan benefit and today's market could be a powerful combination.
Source: Keeping Current Matters
The information contained, and the opinions expressed, in this article are not intended to be construed as investment advice. Keeping Current Matters, Inc. does not guarantee or warrant the accuracy or completeness of the information or opinions contained herein. Nothing herein should be construed as investment advice. You should always conduct your own research and due diligence and obtain professional advice before making any investment decision. Keeping Current Matters, Inc. will not be liable for any loss or damage caused by your reliance on the information or opinions contained herein.
Keeping Current Matters is a trademark of Keeping Current Matters, Inc. CrossCountry Mortgage, LLC; its subsidiaries; and its affiliates have not been authorized, sponsored, or otherwise approved by Keeping Current Matters, Inc. or any of the above-mentioned companies.