

Blog Post
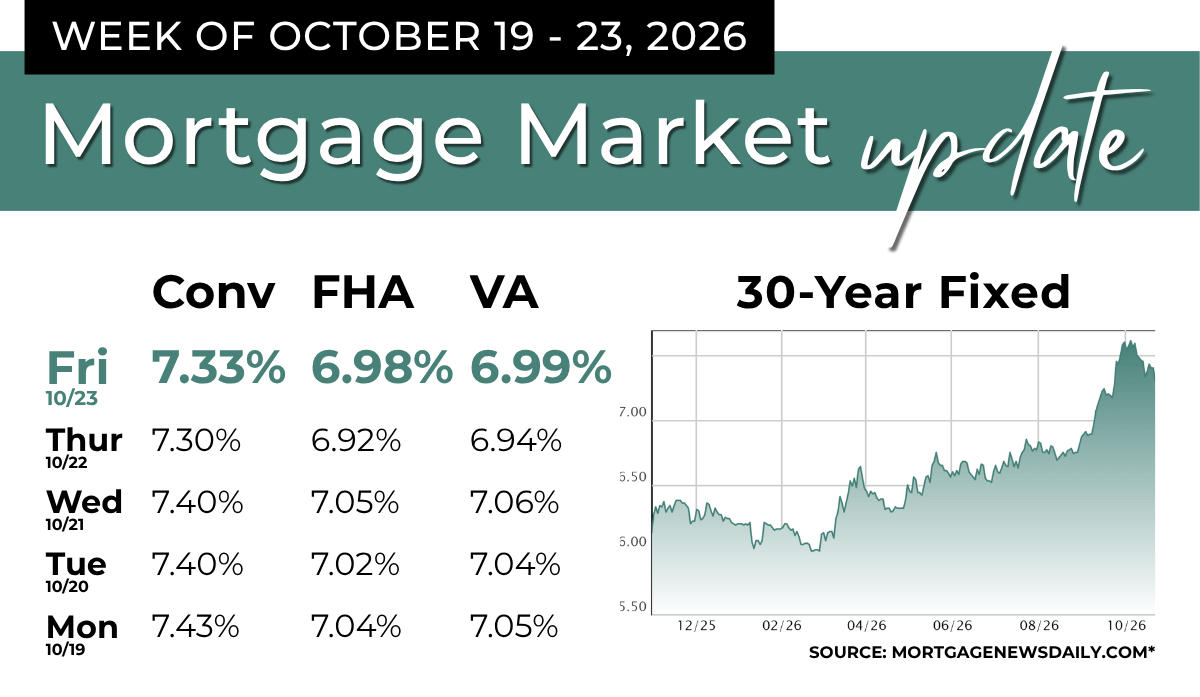
Mortgage rates got some help from the stock market this week, of all places, and finished slightly lower than last week.
The housing market could be working in your favor too. Contract signings hit their lowest level since tracking began in 2001, and fewer people shopping may mean fewer offers to compete with.
If you’ve had your eye on a home, ask your agent how much interest it’s getting. You may find less competition than you’d think. Already under contract? Talk with us about whether to lock your rate before next week’s Fed meeting.
Get in touch, and we’ll help you figure out your next step.
Rate Source: MortgageNewsDaily.com
*The Mortgage News Daily index attempts to capture the most prevalently quoted conventional, FHA, and VA 30-year fixed rates for highly qualified homebuyers that meet the appropriate down payment requirements and have no major loan-level price adjustments.
Mortgage News Daily is a trademark of Mortgage News Daily, LLC. CrossCountry Mortgage, LLC; its subsidiaries; and its affiliates have not been authorized, sponsored, or otherwise approved by Mortgage News Daily, LLC or any of the above-mentioned companies.


