

Blog Post
You’ve spent years making your house feel like home, celebrating milestones, making each room your own, and turning neighbors into friends. As you look ahead to the next chapter of your life, it’s natural to wonder if this is still the place you want to spend it.
Whether you’re leaning toward staying in your house as you get older or moving to a 55+ community, the goal is the same: a home that fits the life you want, with more time for the people and things you love. So, here’s what to consider before you decide.
Wanting to stay in a house you love and are familiar with makes sense. But most houses need at least some updates to make aging in place easier.
In fact, the Joint Center for Housing Studies of Harvard University (JCHS) finds that fewer than 4% of homes have the basics, like single-floor living, no-step entries, and wide hallways and doorways (see graph below):
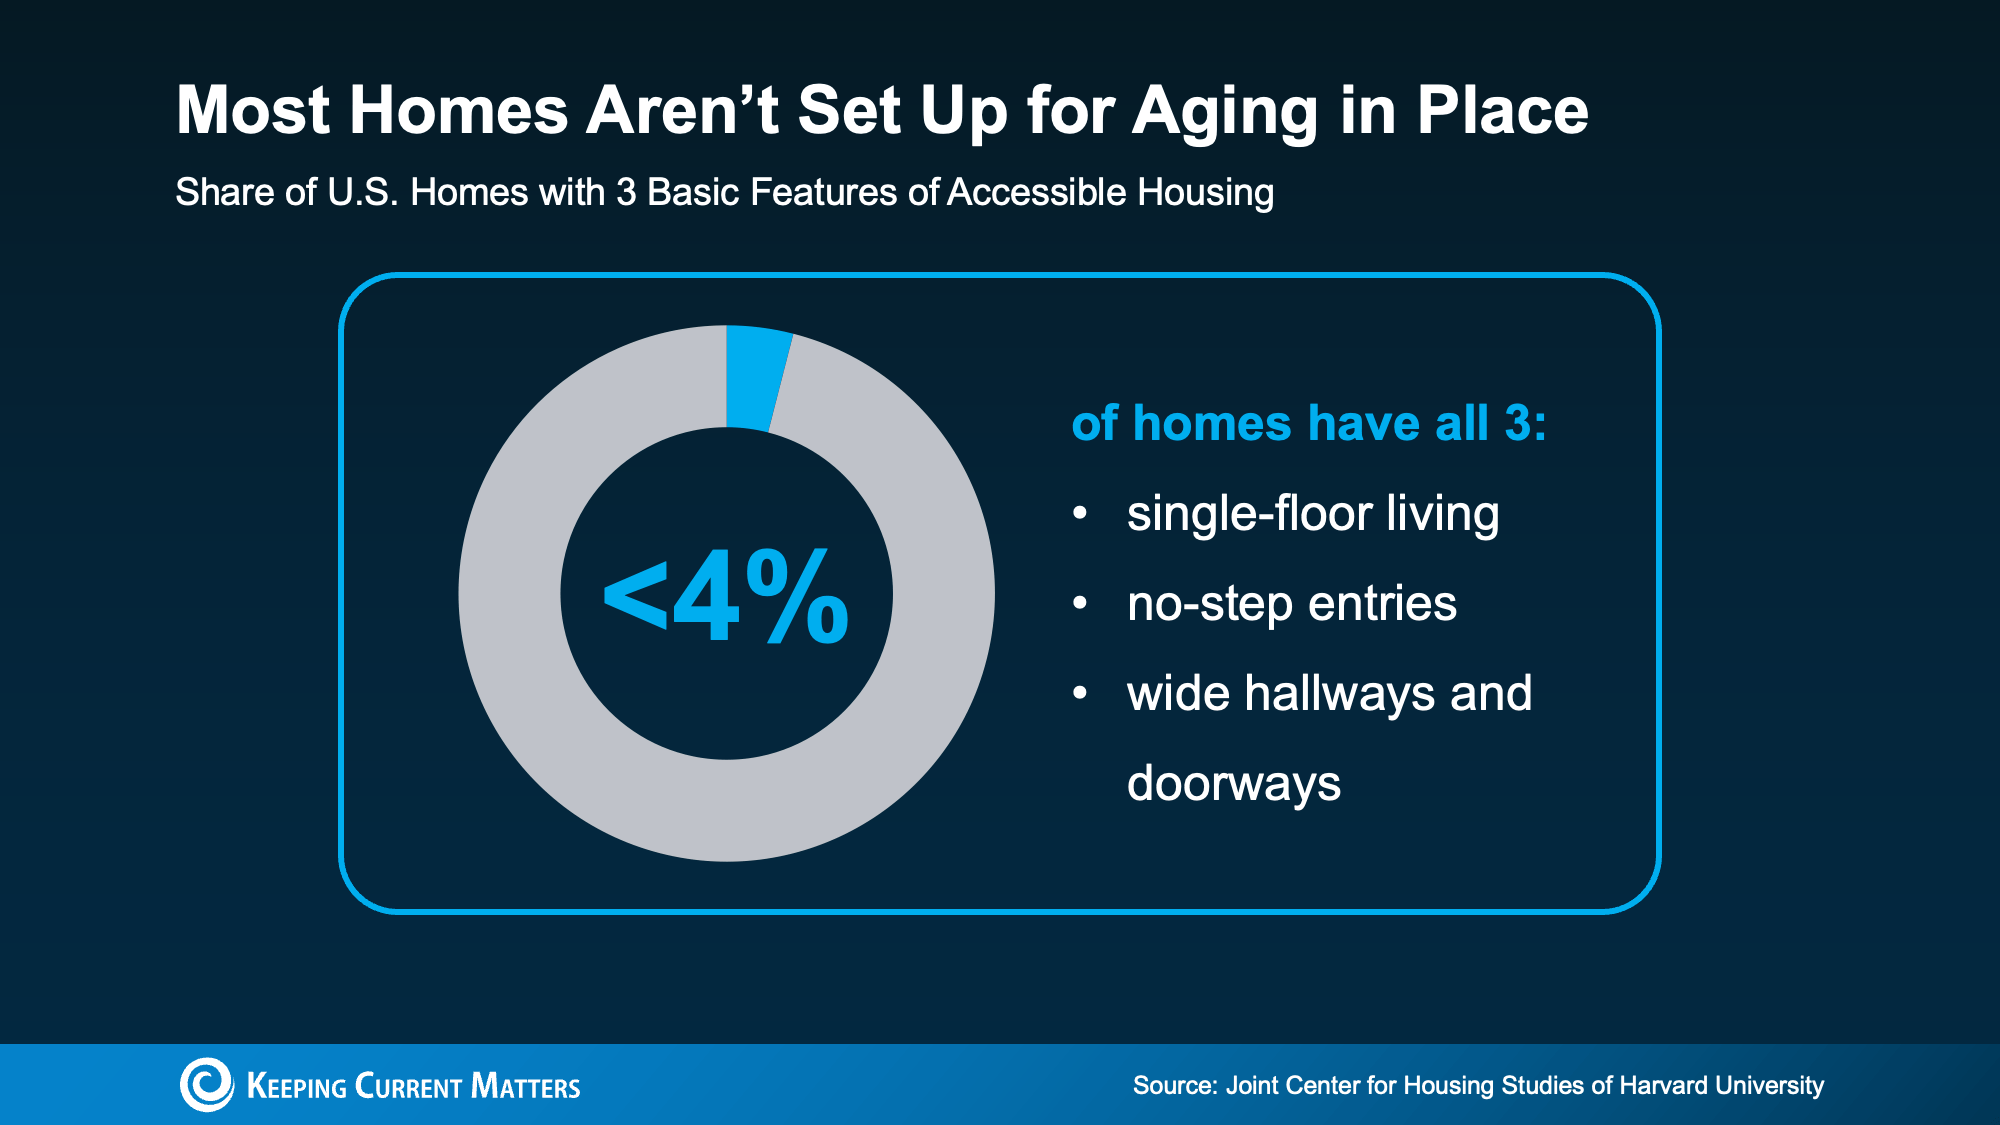
That means for most homeowners, staying put means doing a remodel.
The National Association of Home Builders (NAHB) reports more than half of remodelers (56%) take on this kind of work. Some of the most common projects are installing grab bars, curb-less showers (walk-in showers with no ledge to step over), and wider doorways.
Now, that’s not to say you can’t go this route. You most certainly can. But if this is how you’re leaning just know you’d be living with contractor noise and dust until the work gets done. Some people don’t want to live in a construction zone. Not to mention, having to manage the contractors and schedules, etc.
If that sounds like something you’d rather avoid, here’s the good news. The money for your next home may already be sitting in your current one. It’s called equity, which is the difference between what your house is worth and what you still owe on it. After years of mortgage payments and rising home values, it adds up. Jess Catorc, Co-Founder of Carry, explains:
“The way home equity builds and is used changes a lot depending on your stage of life. . . . For older homeowners, decades of mortgage payments and home-value growth can turn equity into a financial cushion.“
When you sell, that cushion can go toward a home that’s ready for this stage of life. No demo required. You just get the keys and it’s all there, ready for you. That means less time on projects and more time for living. And one option you may consider if you’re entertaining a move is a 55+ plus community.
From the homes to the shared spaces to the activity calendar, these communities are planned around this stage of life. And that means everything you need is already rolled into one place. Rocket Mortgage lists some of the biggest perks (see visual below):
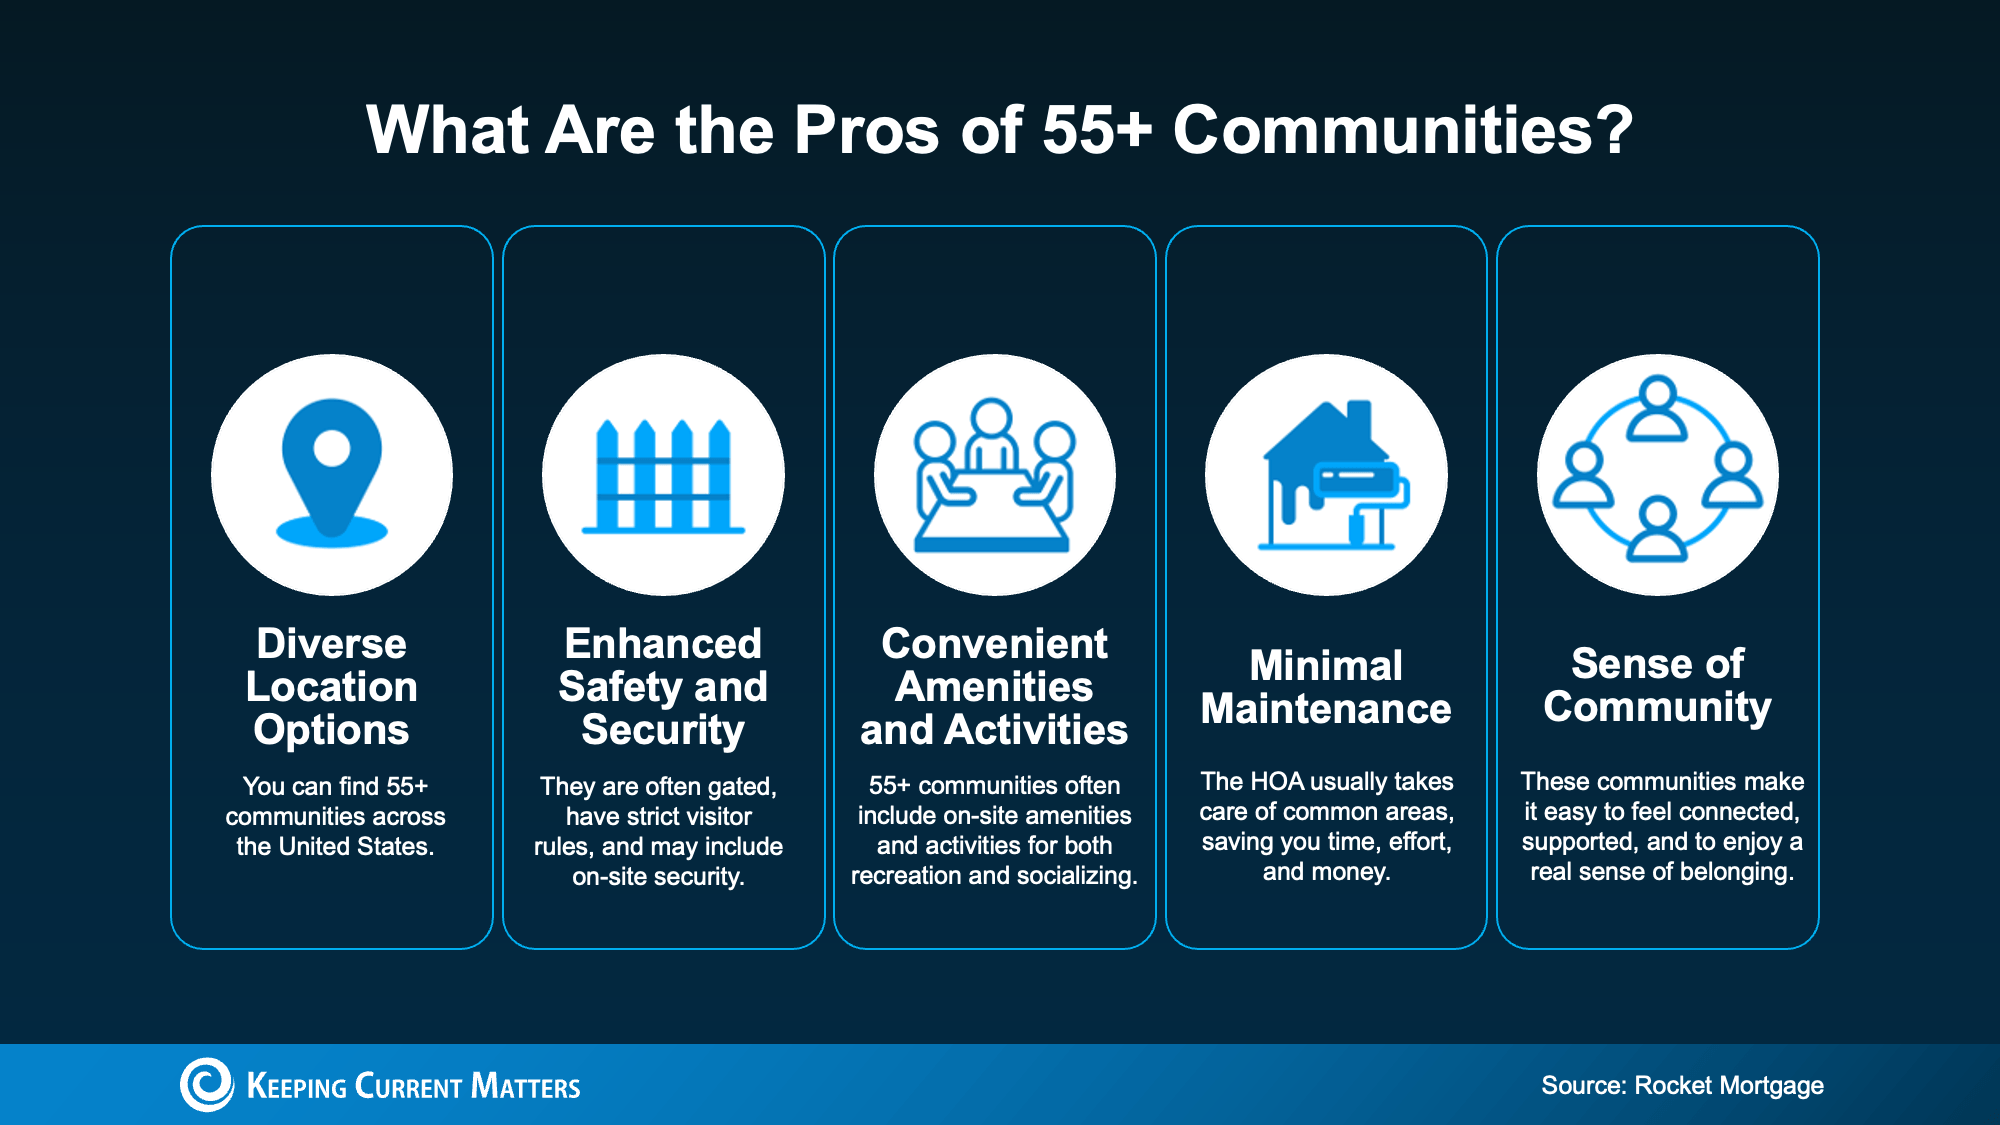
Instead of spending time and money to make your house easier to live in, you’d move into a community that’s designed with that in mind from the jump. That frees you up for the good stuff, like a morning walk with a neighbor, a game night down the street, or finally trying the hobby you’ve been putting off.
Staying and moving can both be good choices. What matters most is finding the place where you'll feel comfortable and at home for years to come.
A local real estate agent can help you weigh the two by showing you what your house could sell for and what 55+ communities in your area have to offer, so you can decide what feels right for you.
Reach out, and we’ll help you figure out your next move.
Source: Keeping Current Matters
The information contained, and the opinions expressed, in this article are not intended to be construed as investment advice. Keeping Current Matters, Inc. does not guarantee or warrant the accuracy or completeness of the information or opinions contained herein. Nothing herein should be construed as investment advice. You should always conduct your own research and due diligence and obtain professional advice before making any investment decision. Keeping Current Matters, Inc. will not be liable for any loss or damage caused by your reliance on the information or opinions contained herein.
Keeping Current Matters is a trademark of Keeping Current Matters, Inc. CrossCountry Mortgage, LLC; its subsidiaries; and its affiliates have not been authorized, sponsored, or otherwise approved by Keeping Current Matters, Inc. or any of the above-mentioned companies.


