

Blog Post
Ask a couple people how the housing market is doing and you’ll probably get a couple different answers. That’s because right now, the market runs on 2 very different tracks, split by price point.
Knowing which track your house is on changes everything about your sale, from your asking price to how long you can expect to wait before an offer comes in. Here’s what you need to know.
Rates and buyer competition are shaping this market differently depending on price point. Look at recent sales data from the National Association of Realtors (NAR) and the pattern jumps right out.
Homes priced under $250,000 saw sales drop 2-3% compared to last year, while homes priced above $750,000 saw sales climb by double digits (see graph below):
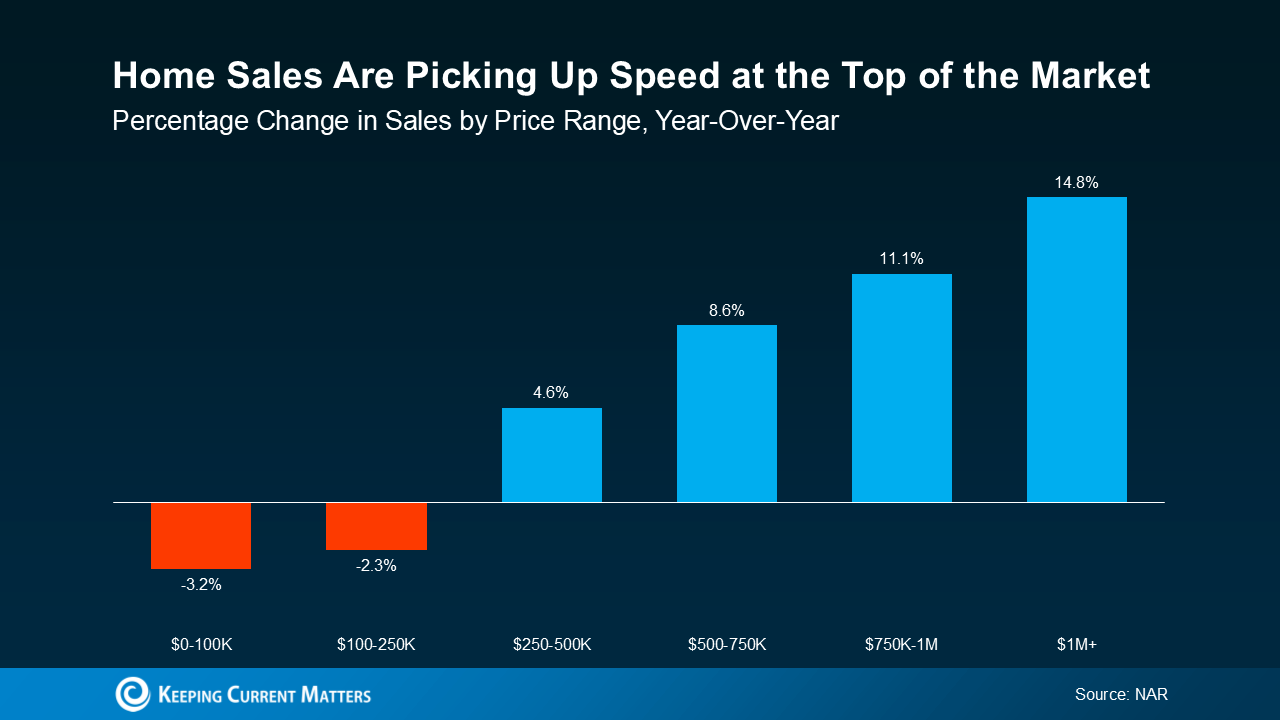 What’s behind the divide? Due to higher rates and the last few years of home price appreciation, fewer buyers can comfortably afford homes at the entry-level price point right now – especially first-time buyers. So, demand in that segment has slowed down.
On the flip side, buyers looking for higher-priced homes have less sensitivity to high-rate environments and more room in their budgets, thanks in part to a strong stock market and their equity in their current home.
That’s the real differentiator. Lower-priced homes are still selling, just not as quickly since today’s rates have shrunk the pool of buyers who can afford to buy their first place right now.
This is exactly why pricing strategy and presentation carry more weight than they used to, especially if you’re selling in that range. Price it right from the start instead of testing a high number, make sure it shows well online and in person, and lean on an agent who can get your listing in front of every buyer shopping in your range. That’s the best way to make sure you catch the attention of one of the buyers who are still looking – and it’s how you prove your home is worth it’s price.
How fast a home sells is shifting by price point too, and the split is just as sharp. For years, luxury homes sat on the market a lot longer than starter homes. That gap has nearly closed, according to Redfin (see chart below):
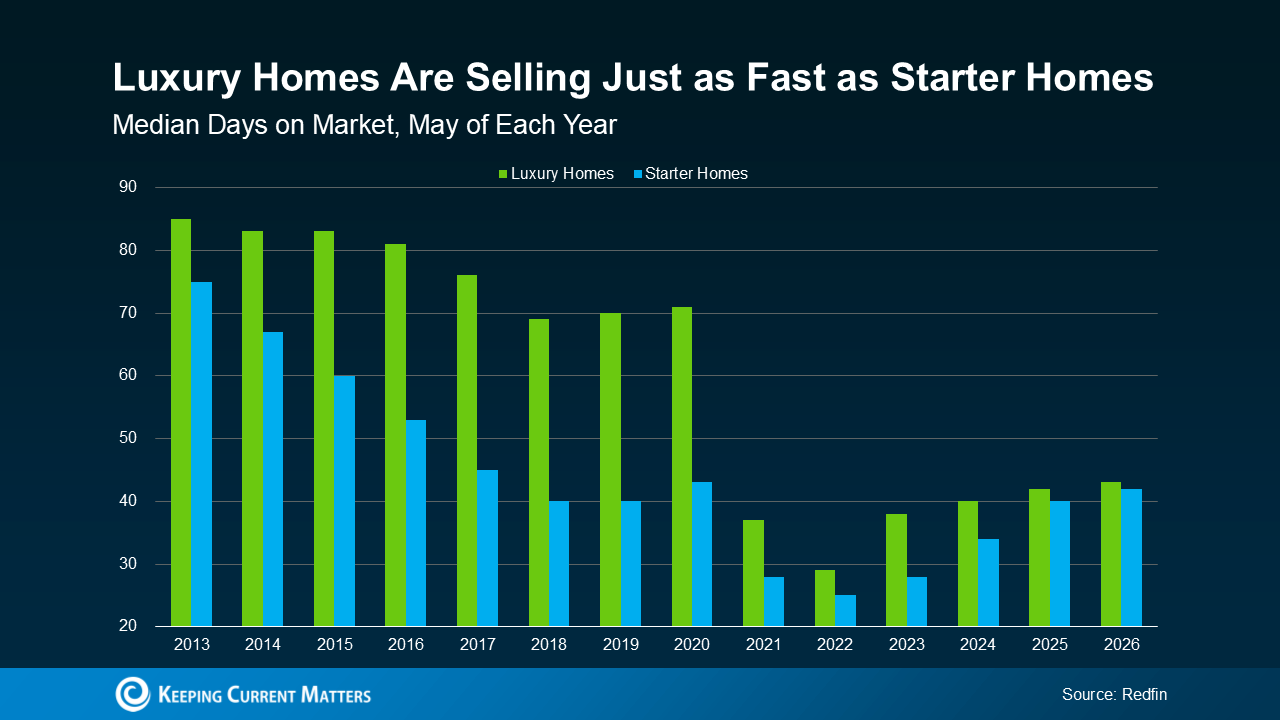 Buyers with deep pockets are moving fast when a well-priced home in their range comes up. As Zillow puts it:
“The U.S. housing market is splitting in two. Luxury homes are selling at a faster pace than a year ago, with shrinking supply and growing bidding wars.”
If you’re in that range, your house may sell faster than you’d expect. You may even get multiple offers. That kind of competition changes how a listing should be marketed and priced from day 1.
And no matter which side you’re on, that’s information you’re going to want up front if you want to have the smoothest sale possible.
If you’re thinking about selling an entry-level home, don’t panic. Homes at your price point are still selling, just at a slower pace than last year. That slower pace means pricing and presentation matter even more right now.
If you’re selling a move-up or luxury house, you’re in a good spot right now. Buyers looking in your price point usually aren’t as affected by today’s rates, so they’re more active, and good listings are drawing real competition.
Either way, your price point is the biggest factor in how fast your house sells and what it sells for.
Your home's price point is the real story right now, more than anything you're hearing in national headlines. Connect with our team to map out exactly where your house fits in this split market and build a pricing strategy that gets you the speed and price you're after.
Source: Keeping Current Matters
The information contained, and the opinions expressed, in this article are not intended to be construed as investment advice. Keeping Current Matters, Inc. does not guarantee or warrant the accuracy or completeness of the information or opinions contained herein. Nothing herein should be construed as investment advice. You should always conduct your own research and due diligence and obtain professional advice before making any investment decision. Keeping Current Matters, Inc. will not be liable for any loss or damage caused by your reliance on the information or opinions contained herein.
Keeping Current Matters is a trademark of Keeping Current Matters, Inc. CrossCountry Mortgage, LLC; its subsidiaries; and its affiliates have not been authorized, sponsored, or otherwise approved by Keeping Current Matters, Inc. or any of the above-mentioned companies.


